by D.J. Webb
The rise to power of Andy Burnham on the back of a mendacious promise made to the people of Makerfield not to reopen the Brexit debate has put rejoining or a large reset that largely destroys the point of Brexit firmly on the table. Establishment news outlets are happy to insist that Brexit has been a disaster and that we are all poorer as a result, apparently attributing all negative effects of Covid and the war in the Ukraine to Brexit. Yet the recent news that GDP was up by 0.7% quarter on quarter in the third quarter and up by 1.9% year on year puts a different light on the story. The fact that the majority of investment in Europe in artificial intelligence is being received by one country—the UK—lies behind the stronger performance. The UK is not constrained by the EU regulatory environment that has slowed the roll-out of AI on the continent. It would be a very bad mistake to agree to align our AI regulations with Europe, thus removing a clear advantage of Brexit. There is reason to believe that if we just hold course, real daylight will open up between the UK and countries like France—although progress would be faster if we diverged in other respects, including by junking Net Zero. Let’s look at the actual GDP results since 2016:

The UK economy was 122.2% of that of France in 2016 in 2015 international dollars as measured by the World Bank. By 2025, the figure was 122.7%. It may not be much to write home about that we have only just done better than France, but clearly there has been no relative collapse in performance. The worst year was 2020, the very date of Brexit and also of the onset of the pandemic. Since then we have recovered our relative standing fully. You wouldn’t know this if you were depending on the mainstream media for your information. In fact, French statistics show French GDP down by 0.1% year on year in Q3, which means our +1.9% result is likely to mean that in 2026 the UK economy as a percentage of the French economy rises to a recent high (I’m basing this on the figures going back to 2013; I haven’t checked to see what the entire historical back-series would show before 2013). A back-of-the-envelope calculation would suggest that the UK economy in 2026 may end up 125.1% that of France.
International organisations, especially the International Monetary Fund (IMF) have been keen to downplay the UK’s prospects ever since Brexit. A long-standing convention is that the senior officials of the IMF are European, not American, and they have their own biases. The IMF produces twice-yearly forecasts, the World Economic Outlook, which has regularly had to revise up its forecasts of UK growth:
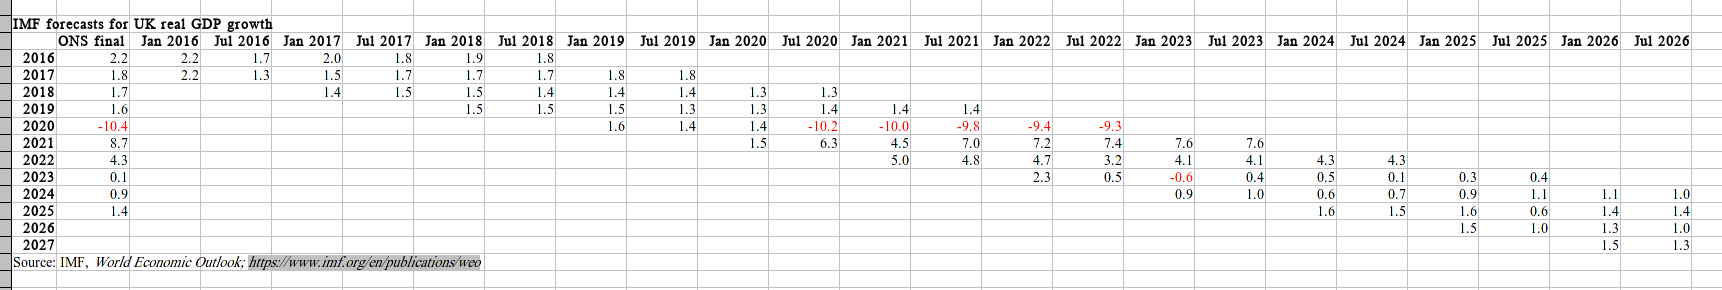
You will notice that in 2016 the IMF originally expected 2.2% growth, suddenly revised down to 1.7% after the Brexit referendum. Then a series of forecasts and estimates gradually revised that up again, and the final result was the 2.2% originally forecast in January 2016. The forecast for 2017 was smartly lowered from 2.2% to 1.3% because of the Brexit referendum, but the outturn (ONS final in the image above) was 1.8%. The full-year recession the IMF at one point forecast for 2023 didn’t happen. The 1% growth rate the IMF has forecast for 2026 now looks overly pessimistic, given that GDP was up by 1.9% year on year in Q3. Let no-one imagine these IMF forecasts are the result of careful analysis.
I think you could argue that Britain could have growth faster than France, or was even all set to grow faster than France in the absence of Brexit. This is because there was a large fall-off in foreign direct investment (FDI) in the early years of Brexit, when uncertainty was at its highest. What is the evidence that Britain could have done better?
On December 10th 2020, The Economist argued the following:
The British government’s own modelling suggests that under such an accord, Britain’s GDP will be 5% lower in 15 years than it would have been had the country stayed in the EU. With no deal, the cost rises to 8%.
By September 5th 2024, The Economist was saying:
Slapping a number on the cost of Brexit is tough: there is no easy counterfactual. Worse, Britain formally left the EU in January 2021, while covid-19 lockdowns were still warping economic data. Economists’ best stab uses a “Doppelgänger” model to approximate no-Brexit Britain to a weighted average of countries that performed similarly before 2016. That usually lands on a one-off hit to GDP from Brexit of 5%, which is also near the rough 4% assumption of the Office for Budget Responsibility, Britain’s fiscal watchdog.
That figure may well be a little high. Compared with its closest peers, Britain’s growth since 2016 has been shabby but not uniquely disastrous: better than Germany but worse than France and much worse than the Netherlands or Switzerland. Many countries with similar pre-2016 records to Britain outperformed it afterwards for unrelated reasons: America was supercharged by fiscal expansion; Canada and Australia rode a post-covid commodity boom. But even a more cautious estimate, of around 2-3% of GDP, would make Brexit one of the rich world’s worst economic blunders.
By 2024, therefore, The Economist was already admitting the 5% hit was nonsense, and had revised it down to 2-3%. This is because claims that Britain could have growth as fast as America, Canada and Australia were invalid, because those countries had special factors, including a commodity boom. Maybe The Economist should have realised that in 2020. (Brexit was not “one of the rich world’s worst economic blunders” if the potential for regulatory divergence, using our Brexit freedoms, is eventually used. Cancelling Net Zero would single-handedly make it all worthwhile.)
By December 30th 2025, The Economist was back to saying the hit was 6-8%:
The latest skirmish over numbers came in November, when the US-based National Bureau of Economic Research (NBER) published a paper finding that leaving the EU has already reduced British GDP per person by 6-8%. That is well above the predictions made during the 2016 referendum campaign, when the average forecast suggested GDP would be 4% lower in the longer term—a figure that Britain’s fiscal watchdog, the Office for Budget Responsibility, still considers accurate.
Julian Jessop, a Leave-supporting economist, says the NBER study fails the “smell test”. Its macro estimates benchmark Britain against 33 countries, including America, whose economic outperformance since the pandemic makes it a tricky comparator. Strip America out and Britain’s record has been fairly average among the G7 group of large rich countries. GDP per person grew by 3.9% between 2016 and 2024—less than in France and Italy, but more than in Germany and Canada. This suggests that if the NBER figures were correct and Brexit had not happened, Britain would have grown much more strongly than France or Germany. Mr Jessop is right that this counterfactual smells a bit whiffy.
That magazine once again admits that including America in the basket of comparison countries distorts the figures and that it is a “bit whiffy” to claim that Britain would have grown much more strongly than France or Germany. There is also sleight of hand in the article, because in the last paragraph quoted, The Economist shifts from discussing GDP growth to growth in GDP per capita (GDP per person grew by 3.9% between 2016 and 2024—less than in France and Italy, but more than in Germany and Canada), but the Boriswave of migrants means that GDP per capita growth will be much harder to achieve over the period discussed, simply because the population grew so much. In fact, the World Bank figures quoted above show that Britain has outperformed France and Germany in terms of growth in GDP itself. The following chart shows what happens to those figures once population growth is factored in:
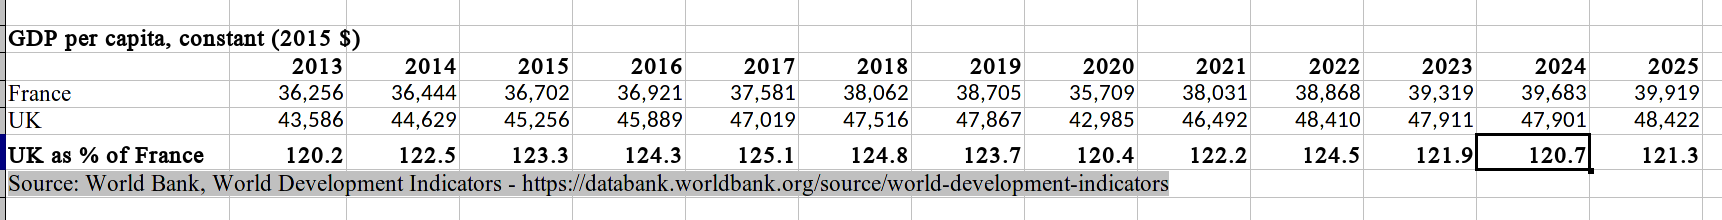
This chart does show that GDP per capita was 124.3% of the French figure in 2016, but 121.3% in 2025. These figures suggest that there may have been some kind of hit over the worst period of Brexit uncertainty. However, the past ten years have been uniquely chaotic for the global economy. The pandemic, which increased national indebtedness a lot, and the election of a Labour government that put up taxes by a lot as a result have taken their toll too. Even factoring in the Boriswave, in 2022 GDP per capita was 124.5% of the French figures—above the 2016 figure—and the fall has only really been over the last three years as our taxes have gone up and up. And yes, migration numbers have remained historically high.
In any case, claims the Brexit hit might have been 5%, or 6%, or 8%, make the bizarre assumption that the UK could have been a miracle economy outperforming all other leading economies even during the pandemic and then throughout the current period marked by a spike in oil prices. There is also nothing in this analysis for Britain’s destructive Net Zero policies. UK electricity prices for businesses are 50% higher than in France and at least three times those in the US. To have slightly outpaced French GDP growth in 2016-25 despite the higher electricity prices isn’t a disastrous performance.
It is worth considering UK trade performance. Briefings for Brexit has argued that most of the fall in UK exports to the EU reflects special factors. These special factors account for at least £20bn of the £26bn fall in UK exports to the EU. These include a methodological shift removing apparel re-exports from UK trade data, the role of lower North Sea oil and gas production in UK petrochemical exports, the role of weak EU automotive production in hitting UK auto parts exports to the EU and the long-term decline in pharmaceutical exports that has been in train since at least 2009. The Briefings for Brexit article is worth reading to understand the large number of special factors that have been in play in recent years.
Nevertheless, the UK is not one of the most trade-intensive countries. Goods exports only account for less than 13% of GDP (see government figures on this). Services exports (financial services, tourism, AI and much else) account for 17-18% of GDP. The fact that services exports are doing so well more than offsets weakness in goods trade. In fact in 2025, goods exports from the UK were down by 1.2%, whereas services exports were up by 7.3%, with the result that goods and services exports combined were up by 3.5% in 2025. In any case, the non-EU market accounted for 59.7% of exports in 2025. Britain cannot solely focus on a Brexit reset that would allow the EU to sell more to the UK. It has other markets, and in any case the Brexit debate revolves almost entirely around goods trade, a less important area overall for UK GDP and one that ignores the prominence of services exports. It may be that some comparatively small areas of export trade would benefit from an improvement in trading terms with the EU—but this cannot come at the expense of our right to trade with the rest of the world on terms we choose and to vary out regulations as we see fit.
Clearly no Brexiter was expecting the UK to leave its new Brexit freedoms ENTIRELY UNTOUCHED. The gap that has opened up in regulations reflects the fact that the EU has regulated further—thus allowing the UK to emerge as a more logical locale for AI investment. Having performed much the same as France overall since 2016, we should be using our Brexit freedoms to boost GDP growth. Even if we don’t, the AI boom could give us a boost vis-à-vis France anyway, and this seems to be in progress, but this is a very passive approach to Brexit, allowing any improvements to come our way almost accidentally. Nevertheless, the role of AI in boosting GDP growth at present underlines the importance of not agreeing to dynamic alignment of regulations with the EU. Over time, our advantages from not following every foolish piece of regulation will gather in importance and allow us to steal a march on our neighbours. We need to:
- Get rid of Net Zero in its entirely, authorise all North Sea oil and gas developments speedily and allow fracking throughout the UK. We should certainly not join the EU carbon market, which would single-handedly make Brexit pointless.
- We should make sure that our AI regulations are the lightest-touch in the world. There should be no alignment of them with the EU. We should look at Japan’s light-touch to AI and make sure our regulations are no stiffer. We should not be enticed by the argument that AI is just about to take over the world Terminator-style. That is science fiction and ultimately Luddism.
- Britain should offer funding for AI start-ups and set up Singaporean-style links between university research teams and industry to ensure that AI that is developed is also commercially developed in the UK and not just sold abroad.
- Theresa May’s government had pushed for the UK’s pharmaceuticals sector to continue to be overseen by the EU’s European Medicines Agency. This was abandoned by the Johnson government in 2020, and must not make a comeback under Burnham. We need to be able to roll out medicines more quickly than the EU.
- We should junk the General Data Protection Regulation (GDPR) provisions that the technology sector objects to. We need to work out why the UK has no Amazon, Ebay, Twitter, Google or Microsoft. We need to offer tech start-ups capital and know-how to get off the ground—and to stay in the UK.
As Lord Frost recently wrote:
Nearly half of British voters think that we are as rich, or richer, than Switzerland. Over half think we are as rich or richer than Australia, Singapore, or Germany. And, incredibly, over half of us think Britain is as rich as, or richer, than the United States.
The truth of course is that we are poorer than all those countries – according to the IMF, we are10 per cent poorer than Germany, 20 per cent poorer than Australia, about 40 per cent poorer than America or Singapore (remember all those “Singapore-on-Thames” scare stories? If only), and only half as rich as the Swiss.
Britain needs a more realistic evaluation of itself. Most UK politics revolves around the idea that the UK is so rich it can afford to take in millions to sit on benefits, to hand out billions to Mauritius, to offer slavery reparations to people who were never enslaved and to hand over billions to the Ukraine. In fact, Britain is one of the poorest of the so-called advanced countries and needs to face up to its decline. We would need to nearly double the size of our GDP to rival the living standards of Singapore. In the end, the EU is a club for declining countries that want to shut out the world market while they all decline together. Brexit gave us an opportunity to get out of the rut. It’s an opportunity we have chosen not to make the most of. The AI boom shows there could be life in the old dog yet. Burnham, don’t ruin it!

Discover more from The Libertarian Alliance
Subscribe to get the latest posts sent to your email.